

Piggy Bank Allowance - Bomad
4.4

Allowance systems often fail for a simple reason: the child hears a promise, the parent forgets the details, and the money becomes a vague conversation at the end of the week. I tested Piggy Bank Allowance - Bomad as a way to make that routine visible. It is a free parenting app from Graeme P that turns pocket money into a digital record, with separate places for saving and spending. That sounds modest, but the separation changes how a family can talk about money.
My first impression is that this is not trying to be a full banking product for children. It is closer to a shared household tool for tracking allowance decisions. The child can see progress toward a goal, while the parent has a clearer way to record what was earned, saved, or used. For families who want to teach basic money habits without handing a young child a payment card, that focus makes sense.
From an informal promise to a visible allowance routine
The most useful place to begin is before opening the app. Imagine a child asking for a new toy after completing several chores. In a traditional arrangement, the parent might say, “You have earned some money,” then calculate the amount mentally or search through notes and messages. The child may spend it immediately, and the saving lesson disappears.
With this app, I would first agree on the rule outside the screen: which tasks count, when the allowance is reviewed, and what portion is intended for saving. The app is then used to record the outcome rather than decide the family’s values for it. That distinction matters. It can organize a routine, but it cannot replace a clear agreement between parent and child.
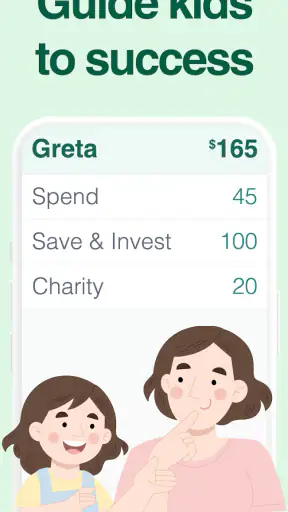
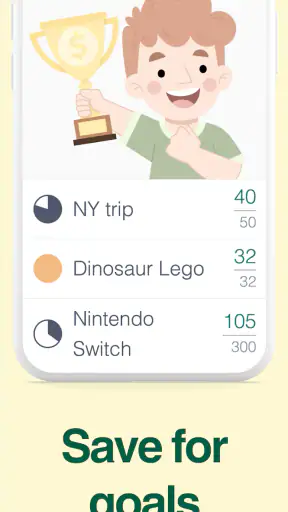
I found the saving and spending jars or pots especially useful because they give the allowance two different destinations. A child who sees one undivided balance may treat every amount as available. Separating the money creates a small pause before spending. It also makes a parent’s explanation more concrete: some money is for today, while some is being kept for something larger.
That structure works well for younger children who understand visible containers better than abstract budgeting. It can also help older children who are beginning to manage several goals. A family might use one place for everyday treats and another for a planned purchase, rather than presenting saving as a lecture.
The app is rated for Everyone, which fits its family-oriented purpose. I would still use it with an adult nearby at first, not because the concept is difficult, but because the important part is agreeing on what each entry means. A child should not have to guess whether an amount represents money already received, money promised, or money still waiting for a chore.
Setting up the first realistic cycle
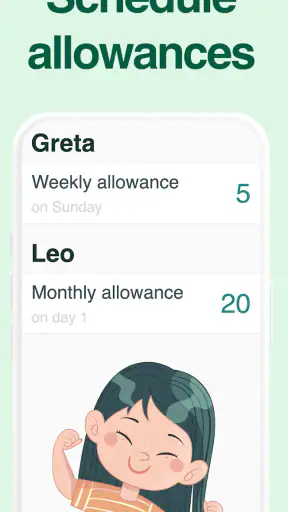
A good first test is a short, ordinary allowance cycle rather than a complicated long-term plan. I would choose one weekly review day and keep the first goal simple. For example, after the child completes the agreed tasks, the parent records the allowance and places the chosen portion into the saving jar. The child then checks the result and says what the money is for.
This workflow creates three separate moments: earning, recording, and deciding. That separation is one of the app’s practical strengths. It prevents the parent from treating a completed chore and a purchase as the same event. It also gives the child a chance to see that money can remain untouched and still be making progress toward something.
A useful tip is to name the purpose of saving in everyday language when the family discusses it, even if the app itself is simply being used as a container. “Bike fund” or “birthday gift” is easier for a child to remember than “long-term savings.” The app provides the visual place; the conversation supplies the meaning.
I would also avoid changing the rules every time the child asks for something. If the parent moves money between the saving and spending pots impulsively, the record becomes less helpful. The better workflow is to decide the split during the allowance review, then treat an extra transfer as a separate family decision. That keeps the history understandable.
How the handoff works between parent and child
The handoff is where this kind of tool either becomes useful or becomes another screen nobody checks. The parent usually supplies the information: what was earned and where it belongs. The child supplies the motivation: choosing a goal, watching progress, and deciding when spending is worthwhile. If only the parent uses the app, it risks becoming private bookkeeping.
I would make the handoff part of a regular conversation. After recording an allowance, I would show the child the new balance and ask what changed. If the spending pot increased, the child can decide whether to keep it for a small purchase. If the saving pot increased, the child can estimate how much closer the goal feels. That turns an entry into a learning moment without making every allowance discussion formal.
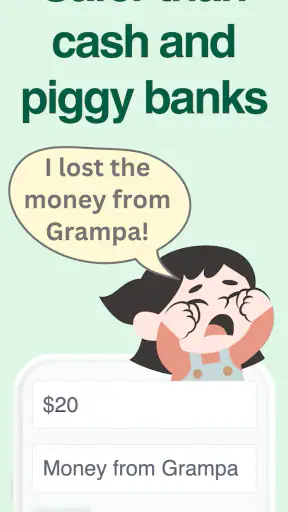
There is also a useful distinction between digital tracking and physical money. A family may still hand over coins or notes, while using the app as the record. Alternatively, the parent may hold the money and treat the app as a promise ledger. Either approach can work, but the family should say which one it is. Otherwise, a child may count the digital balance as cash immediately available when the parent sees it as an amount to be paid later.
This is one of the app’s hidden trade-offs: its simplicity gives families freedom, but that freedom requires consistency. A dedicated banking service may enforce clearer transaction rules, while this app is more adaptable to a household’s own arrangement. For teaching the difference between “earned,” “saved,” and “spent,” I prefer that flexibility. For managing real funds independently, I would look for a more formal financial product designed for that purpose.
Parents should also decide who is responsible for updating the record. If both people assume the other will do it, the balance quickly becomes unreliable. In my preferred routine, the parent records the allowance immediately after the weekly review, and the child checks the jars afterward. That division keeps the entry accurate while preserving the child’s involvement.
A practical example from one week
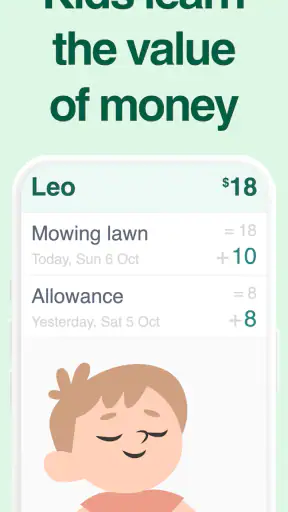
Consider a child who has been saving for a larger item but still wants a small treat. At the weekly review, the parent confirms that the agreed tasks were completed. Instead of handing over one undifferentiated amount, the family records the allowance and divides it between the spending and saving pots. The child can see that buying the treat will affect only the spending side, while the larger goal continues.
Later, the child asks whether the saved amount can be used. This is where the app supports a better conversation than a simple yes or no. The parent can ask whether the child wants to protect the goal or move some money for the purchase. If the decision changes, the transfer should be recorded as a deliberate choice rather than quietly adjusted in the background.
At the end of the week, the outcome is not merely a balance. The child has experienced a complete loop: a task led to an allowance, the allowance was divided, a purchase was considered, and the saving goal either continued or changed. That loop is more valuable than a colorful total because it connects actions with consequences.
For parents, the app can reduce arguments about memory. Instead of debating whether an allowance was already paid, the family has a shared place to check. It will not solve disagreements caused by unclear rules, but it can remove the “I thought you said” part of the dispute.
What the app does better than paper or a general notes app
A notebook is flexible and costs nothing, but it depends on neat handwriting, regular updates, and a child remembering where the page is. A notes app is convenient for adults, yet it often presents money as a list rather than as separate purposes. Piggy Bank Allowance sits between those options: it is more structured than a note and less intimidating than a banking interface.
The jars or pots are the key difference. They create a mental model that a spreadsheet may explain but a young child may not feel. Moving money into a saving space communicates restraint without requiring a lesson about categories, accounts, or percentages. I see this as the strongest reason to choose it over a generic family budget app.
It is also less demanding than a full chore-management system if the family already has another way to track tasks. I would not force every responsibility into the allowance app. Keep the chore discussion where it already works, then use this tool for the money outcome. That narrower workflow can be easier to maintain than an all-in-one system that nobody updates completely.
On the other hand, families wanting automatic payments, card controls, spending restrictions, or a formal record of real transactions should choose a different type of product. This app is best when the goal is understanding and consistency, not financial independence. Its value comes from the conversation around the balance.
Small habits that make the system more reliable
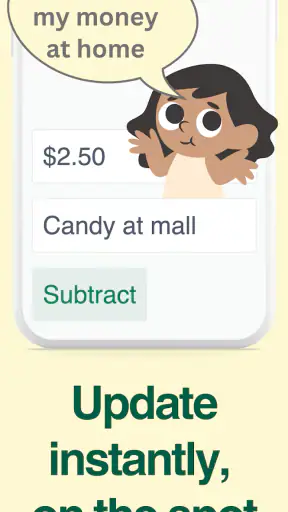
One practical habit is to record changes at the moment they happen. If several allowances and purchases are entered together at the end of the month, the child loses the connection between an action and its result. A short update after each review is more useful than a perfectly reconstructed history later.
Another is to keep the saving goal visible in conversation. The child should know why money is being protected. Without a goal, the saving pot can feel like money that has simply been taken away. The app can show separation, but the parent needs to explain the benefit in terms the child understands.
I would also use the spending pot to practice waiting. When the child wants something small, ask whether the current amount is enough and whether spending it changes the larger plan. That gives the child a decision without making the parent the sole gatekeeper. It is a more realistic lesson than banning all spending or approving every request.
A further insight is that the app can expose inconsistent adult behavior. If a parent occasionally promises an allowance, pays it late, and then changes the amount, the jars will reveal the confusion. That may feel uncomfortable, but it is useful. The family can then revise the routine: one review day, one agreed rule, and a clear note about exceptional payments.
Where the flow becomes awkward
The biggest weakness is that the app cannot create discipline by itself. A parent who forgets to update it will still have an outdated balance, just as with paper. The digital format may make the problem less visible because the screen looks organized even when the entries are incomplete. I would treat regular use as part of the allowance agreement, not as an optional extra.
There can also be friction when a child expects the digital balance to equal money in their hand. Parents need to explain whether the app tracks actual cash, a future payment, or a family promise. If the household changes between those interpretations, trust suffers. This is not a technical flaw so much as a setup issue, but it is important enough to address before the first entry.
The free price makes it easy to try, although the app includes in-app purchases ranging from $1.99 to $29.99 per item. I would begin with the basic workflow and decide later whether any optional purchase is worthwhile for the family. The presence of paid items means parents should review what they are choosing before confirming a purchase, especially when a child is exploring the app.
Another limitation is the narrow scope. If you want detailed chore scheduling, educational lessons, shared family budgets, or direct spending controls, this may feel too small. That is not necessarily a problem; a focused tool can be easier for a child to understand. But families should not expect it to become a complete household finance system.
Device compatibility is also worth checking before setting up a routine. The current version is 2.0.266 and requires at least Android 9. A family using an older device may need to make sure the app can run there before promising the child a new allowance system. Once installed, I would keep the app on the device used during the weekly review so the handoff does not depend on finding it again.
Who will get the most from it
I think this app is a strong fit for parents who want to introduce saving and spending without opening a child bank account. It suits families where an adult remains responsible for the actual money but wants the child to participate in decisions. It is particularly helpful when arguments come from forgotten allowances or when a child spends everything as soon as it arrives.
It can also work for separated households or relatives who contribute to the same child’s allowance, provided everyone agrees on who updates the record. The app does not remove the need for communication between adults, but a shared jar structure can give those conversations a common reference point.
I would be more cautious for teenagers who need genuine independence with payments, formal account statements, or advanced budgeting. They may outgrow the jar metaphor and prefer a tool that reflects real-world banking. Likewise, families with no interest in assigning regular allowance rules may find that a simple conversation is enough.
The app has reached over fifty thousand installs and holds a 4.4 average from around seven hundred ratings, which suggests that its straightforward idea has found an audience. I would not treat popularity as proof that it fits every household, but it does make the app feel like a practical option rather than an experiment with no visible use.
My final take after following the full workflow
What I like most is the clear path from responsibility to result. A parent agrees on the allowance, records it, divides it between saving and spending, and then lets the child make a visible choice. The app does not pretend to teach every part of personal finance. Instead, it gives one important lesson a place to live: money has destinations, and choices change progress.
The best results will come from families that use it during a predictable weekly handoff rather than opening it only after a disagreement. Keep the rules simple, clarify whether the balance represents cash or a promise, and let the child review the jars. Those steps address most of the friction before it becomes a problem.
For a free parenting app developed by Graeme P, it offers a focused way to make pocket money less vague. I would recommend it to parents starting an allowance routine or trying to introduce saving gently. I would skip it if the real need is banking, automated chore management, or detailed financial controls. Within its narrower purpose, though, Piggy Bank Allowance - Bomad gives children a concrete way to see that earning, saving, and spending are connected decisions.
4.4
46.00 Reviews
Pros
- Simple way to track allowances and pocket money
- Helps children build consistent saving habits
- Parents can monitor payments in one place
- Clear records make money discussions easier
- Useful for setting regular financial routines
Cons
- May feel too basic for older teenagers
- Requires consistent parent updates to stay accurate
- Some features may depend on account setup
- Children may need guidance to use it responsibly
- Limited value if the whole family does not participate


